
How proactive retirement planning can turn savings into a sustainable retirement paycheck
After decades of saving, many retirees struggle with the idea of actually spending their money.
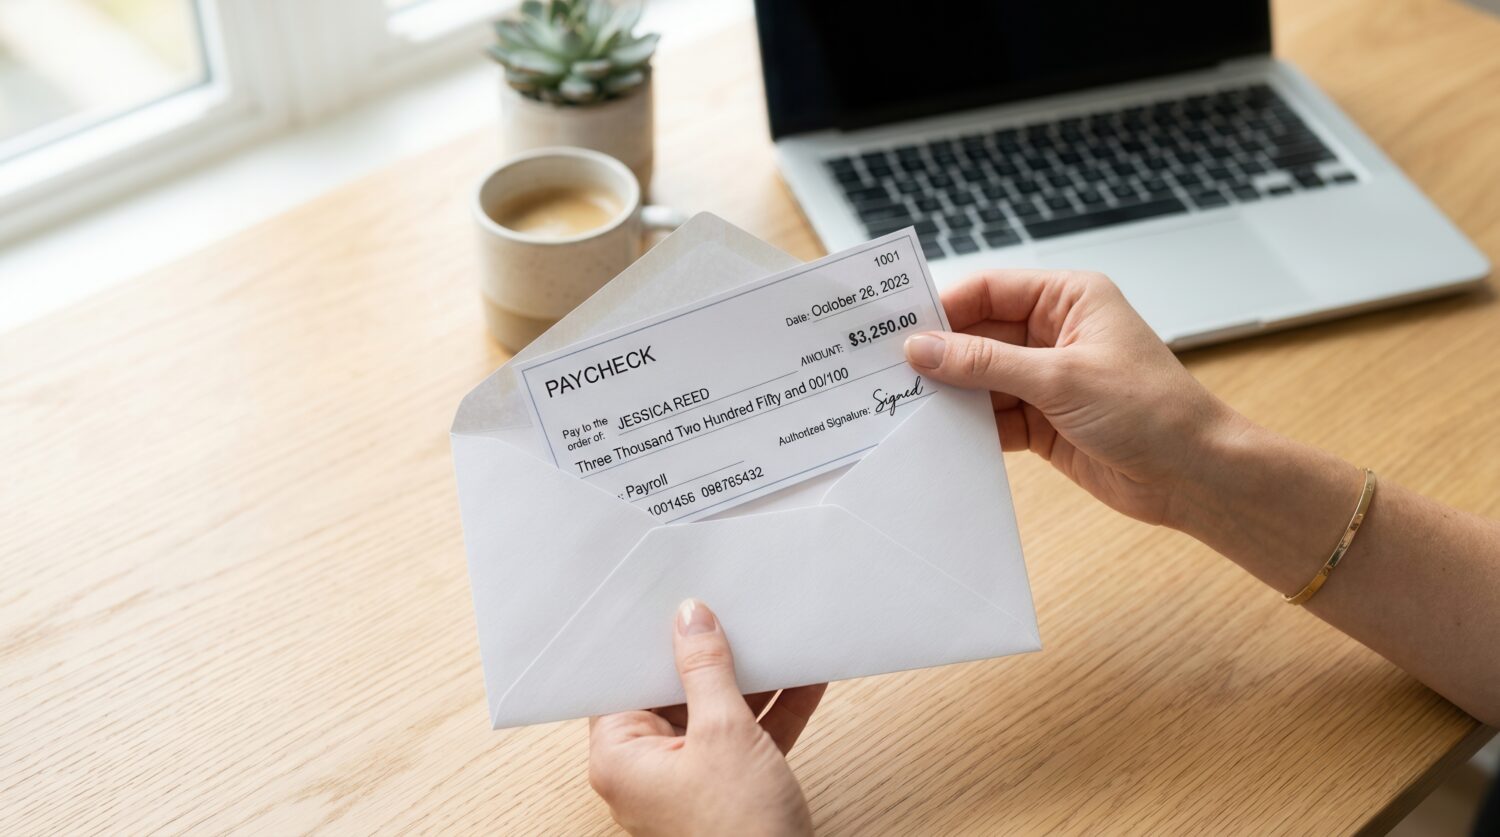
For decades, Americans are encouraged to work, save and build a retirement nest egg. But when retirement finally arrives, the focus shifts from accumulating money to figuring out how to use it.
According to Matt Dages, founder and CEO of Bright Wealth Management, that transition is one of the most overlooked parts of retirement planning.
“That transition is widely overlooked in the aspect of tax planning and income planning and what changes when you start going from collecting a paycheck every two weeks, once a month, whenever you’re getting paid, to then all of a sudden you have to create your own paycheck on a regular basis from your investments, from your savings,” Dages said on the Bright Wealth Management Show.
Start planning before the paycheck stops
Retirement brings important decisions about Social Security, withdrawals, investments and taxes. Dages said those decisions shouldn’t wait until the last day of work.
“You want to have it all ironed out well in advance of actually clocking out for the last time,” he said.
Rather than starting with a specific dollar amount or percentage, Dages said retirement planning should begin with the lifestyle someone wants.
“We need to look at the lifestyle that you want to build and let’s model it backwards and let’s reverse engineer it to say, ‘How do we make this happen with the investments and the savings that you have?’” he said.
Turn savings into a retirement paycheck
After decades of saving, many retirees struggle with the idea of actually spending their money.
Someone might have $1 million saved and still wonder how much they can reasonably withdraw each month. Taxes, inflation, market performance and longevity all factor into the answer.
“A lot of people say, ‘Hey, Matt, I want to take out or I need $5,000 a month.’ … OK, well, we want to net $5,000. You want to see $5,000. So maybe we actually have to take out $6,000 because we have to account for taxes,” Dages said.
That’s why retirement income planning needs to look beyond an account balance and consider how much money a retiree actually needs to spend.
Forget the one-size-fits-all retirement rule
Rules of thumb can be useful starting points, but Dages said retirement planning should reflect an individual’s actual expenses and goals.
“Retirement, it’s never about a percentage. I think it’s just about a lifestyle,” he said. “And I want to build an income plan around that lifestyle that somebody actually wants to live.”
That means separating essential expenses, such as housing, food, utilities, insurance and health care, from discretionary spending such as travel and recreation.
“We’ve got to include everything,” Dages said. “You’ve got to say, ‘OK, well, what are we spending on utilities, on food, on credit cards, on discretionary items?’”
Taxes and AI add new layers of complexity
Taxes can significantly affect how much retirement income someone gets to keep. Dages said tax planning should be part of the retirement strategy from the beginning.
“That’s the basis of understanding your financial plan, getting that income plan, getting that tax plan all together,” he said.
Artificial intelligence can also be useful for researching financial topics, but Dages cautions against treating an AI response as personalized advice.
“The danger isn’t using AI. The danger is confusing the access to the information with the expertise,” he said.
AI can explain a Roth conversion, for example, but it may not understand whether a particular conversion is appropriate, how much should be converted or when it should happen.
Prepare for inflation and market risk
Retirement can last decades, making inflation and market volatility important considerations. Dages said sequence-of-returns risk, experiencing significant losses early in retirement while withdrawing money, should also be modeled.
“We have to look at sequence of returns,” Dages said. “So sequence of returns risk is a big thing that we always want to model out and look at for people.”
The goal is to understand how different scenarios could affect a retirement plan and not to predict the future.
A comprehensive plan can bring together income, taxes, investments, Social Security and expenses to give retirees a clearer picture of where they stand.
Anyone who wants to hear what the Bright Wealth Management team can do for them can claim a complimentary written financial plan online or by calling 480-866-0044.
The Bright Wealth Management Show with Matt Dages airs Saturdays from 1 p.m. to 2 p.m. and Sundays from 3 p.m. to 4 p.m. on KTAR News 92.3 FM.
Related
 Is your retirement account portfolio more concentrated than you think?
 Why it’s important to regularly reevaluate investments when planning for retirement
 Informed decision-making, not following trends, is key to smart investing
 Why preparation is key in creating a plan for retirement savings
 How to make reliable retirement income and why portfolio reviews should be a regular thing
 How building an adaptable retirement plan can help save you money
Comments
0 Comments